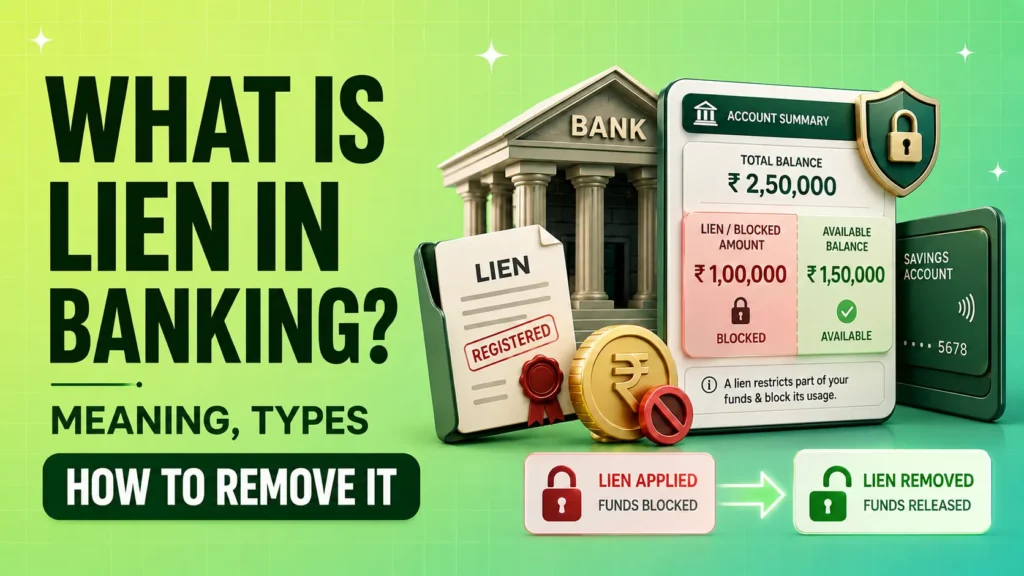
Seeing “lien marked” on your bank account can be confusing, especially when some money becomes unavailable even though it still appears in your balance.
A lien means the bank has placed a hold or claim on a specific amount, deposit or asset because of a particular obligation or instruction. The exact reason can vary, so the first step is to find out why the lien was placed.
Quick Overview
- A lien is a hold placed on a specific amount, deposit or asset.
- The lien-marked amount generally cannot be withdrawn or transferred.
- You may still be able to use the balance above the lien amount.
- Common reasons include unpaid dues, FD security, disputes and authority instructions.
- A lien is different from a complete account freeze.
- The process to remove it depends on why it was marked.
- You should contact your bank if the reason is unclear.
What Is Lien in Banking?
A lien in banking means the bank has the right to hold a particular amount, deposit or asset until an obligation is settled or an applicable instruction is resolved.
For example, suppose your savings account has ₹50,000 and the bank marks a lien of ₹10,000.
The ₹10,000 becomes unavailable for use. If the bank allows it, the remaining ₹40,000 may still be available for transactions.
In simple words:
Lien = Amount or asset placed on hold
The money does not automatically become the bank’s property. The restriction continues until the reason for the lien is resolved.
Also read: What Is Saving Account vs Current Account?
Why Is a Lien Marked on a Bank Account?
There can be several reasons.
Common examples include:
- Unpaid loan EMIs
- Credit card dues
- FD pledged against a loan or credit facility
- Transaction disputes
- Instructions from law-enforcement authorities
- Cybercrime-related complaints
- Certain government or legal orders
- IPO applications through ASBA or an eligible UPI mandate, where the application amount may be temporarily blocked until the allotment process is completed
In IPO-related cases, the blocked amount may appear as a lien, hold, or blocked balance depending on the bank. If shares are allotted, the required amount is debited and the remaining amount is released. If no shares are allotted, the blocked amount is generally released after the allotment process.
The exact reason matters because the removal process can be different in each case.
If you see “lien marked” but don’t know why, don’t assume it is related to a loan. Ask your bank for the reason and reference details.
Also read: What Is a Loan?
What Does “Lien Marked” Mean?
When a bank marks a lien, the affected amount is restricted.
For example:
Account balance: ₹80,000
Lien amount: ₹20,000
Potentially available balance: ₹60,000
The ₹20,000 cannot normally be withdrawn or transferred until the lien is released.
The exact impact can vary depending on the type of lien and the bank’s instructions.
Can You Withdraw Money From a Lien-Marked Account?
Usually, you cannot use the lien-marked amount.
If your account has money above the lien amount, that additional balance may remain available.
For example:
- Total balance: ₹1,00,000
- Lien: ₹25,000
- Remaining balance: ₹75,000
The ₹25,000 is restricted, while the remaining amount may be usable depending on the bank’s restrictions.
If the entire account is restricted, however, you may not be able to make normal transactions.
Types of Lien in Banking
You don’t need to remember complicated legal classifications. For a bank customer, these are the common situations to understand.
| Type of Lien | What It Means |
|---|---|
| FD Lien | An FD is held as security for a loan or credit facility |
| Loan-Related Lien | Funds or assets are held against an outstanding obligation |
| Dispute-Related Hold | A disputed transaction may result in funds being restricted |
| Authority-Related Lien | A bank may restrict funds based on an instruction from a competent authority |
| Banker’s Lien | A bank may retain eligible assets in its possession against certain dues |
The Indian Contract Act, 1872 covers different rights of lien. Section 170 deals with a bailee’s particular lien, while Section 171 provides for the general lien of bankers and certain other specified persons. In banking, Section 171 is particularly relevant because it may allow a bank, subject to applicable law and the circumstances of the case, to retain certain assets or funds until dues are cleared.
General Lien vs Particular Lien
In banking and contract law, a lien is generally discussed as either a general lien or a particular lien. The main difference is the scope of the right to retain goods, securities or other assets.
| Type of Lien | Simple Meaning |
|---|---|
| Particular Lien | The right to retain specific goods until charges related to those particular goods are paid. |
| General Lien | A broader right available to certain persons, including bankers, to retain eligible assets for a general balance due, subject to applicable law and circumstances. |
For bank customers, general lien is usually the more relevant concept. For example, a bank may have rights over certain deposits or securities when money is due to the bank, depending on the loan agreement, account terms and applicable law. However, every blocked amount shown in a bank account should not automatically be treated as a general lien because funds may also be restricted for reasons such as an IPO mandate, legal order or transaction-related hold.
Lien on Fixed Deposit: What Does It Mean?
A lien can also be marked on a Fixed Deposit (FD).
This commonly happens when you use an FD as security for a loan or credit facility.
For example:
FD value: ₹5 lakh
Loan against FD: ₹4 lakh
The bank may mark a lien on the FD. You generally cannot prematurely withdraw or close the deposit while it is serving as security, subject to the applicable terms.
Once the underlying obligation is cleared, the bank can release the lien according to its process.
Also read: FD or RD: Where Should You Invest Your Money?
Lien vs Hold vs Account Freeze
A lien, hold and account freeze can all restrict your access to money, but they do not always mean the same thing.
| Term | What It Usually Means | Can You Use the Money? |
|---|---|---|
| Lien | The bank has marked a specific amount or asset against an obligation, such as a loan, credit facility or other valid claim. | Usually, the lien-marked amount cannot be withdrawn or freely used until the lien is removed. |
| Hold or Blocked Amount | A temporary restriction may be placed on funds because of an IPO application, payment authorisation, pending transaction or similar banking process. | The blocked amount is generally unavailable until the transaction is completed, cancelled or released. |
| Account Freeze | Transactions in the account may be restricted because of KYC issues, regulatory requirements, court orders, law-enforcement instructions or other reasons. | Depending on the type of freeze, some or all debit or credit transactions may be restricted. |
The exact term shown in your banking app may vary from one bank to another. A “blocked amount” or “hold” does not automatically mean that the bank has exercised its general lien. For example, money blocked for an IPO application or a pending transaction may simply be temporarily unavailable under that specific process.
If you are unsure why an amount is marked as lien, hold or blocked, check your account statement or contact your bank and ask for the exact reason and applicable reference or transaction details.
How to Check Why a Lien Is Marked
If you don’t recognise the lien, start with your bank.
Follow these steps:
- Check your banking app or account statement.
- Look for the lien amount and any remarks.
- Contact the bank through its official customer-care channel.
- Ask why the lien was placed.
- Ask for the reference number or details of the instruction.
- Visit the branch if the issue cannot be resolved online.
Do not share your OTP, PIN or internet banking password with anyone claiming to help remove a lien.
How to Remove a Lien From a Bank Account
There is no single removal process because the reason for the lien matters.
If the Lien Is Due to Unpaid Dues
If the lien relates to unpaid EMI, credit card dues or another bank obligation:
- Check the outstanding amount.
- Clear the required dues or fulfil the condition.
- Ask the bank to release the lien.
- Check your account again after the bank processes the request.
Banks may require the dues or underlying condition to be resolved before releasing the lien.
If you notice an unexpected or duplicate EMI debit while checking your loan dues, read our guide on EMI deducted twice to understand the possible reasons and refund process.
If the Lien Is Due to a Transaction Dispute
You may need to provide:
- Transaction details
- Proof of the transaction
- Source-of-funds documents
- Any other information requested by the bank
The bank may investigate the dispute before releasing the restricted amount.
If the Lien Is Due to a Law-Enforcement or Cybercrime Complaint
This situation is different.
The bank may need a revocation or release instruction from the concerned authority before removing the lien.
You should:
- Ask the bank why the lien was placed.
- Obtain the relevant complaint/reference details.
- Find out which authority issued the instruction.
- Provide documents showing the legitimate source of funds, where relevant.
- Follow the concerned authority’s process.
- Submit the required release/revocation document to the bank.
Don’t assume that paying the bank will remove an authority-related lien.
How Long Does It Take to Remove a Lien?
There is no fixed timeline for every lien.
The time depends on:
- Reason for the lien
- Bank verification
- Documents required
- Whether another bank is involved
- Whether a government or law-enforcement authority issued the instruction
- How quickly the underlying issue is resolved
A simple bank-related lien may be resolved after the required condition is fulfilled. Authority-related matters can take longer.
What If the Bank Does Not Remove the Lien?
If you believe a lien has been placed incorrectly or the bank is not giving you a clear reason, first raise a written complaint with your bank. Keep the complaint number, emails, account statement and any other supporting documents for reference.
If the bank does not reply within 30 days, or you are not satisfied with its response, you may be able to file a complaint under the Reserve Bank Integrated Ombudsman Scheme, 2026.
You can submit an eligible complaint through the RBI Complaint Management System at cms.rbi.org.in. The RBI Ombudsman process is free for customers.
A simple escalation process is:
Bank Customer Care → Bank Grievance or Nodal Officer → RBI Ombudsman
However, the RBI Ombudsman may not be the correct route in every lien case. For example, if the bank has placed or continued a restriction while complying with an order from a court, statutory authority or law enforcement agency, the complaint may fall outside the scope of the Ombudsman Scheme. In such cases, you may need to contact the authority that issued the instruction.
Before escalating the complaint, ask your bank for the exact reason for the lien and whether it was created by the bank itself or because of an instruction from another authority.
What Should You Do If Your Account Shows “Lien Marked”?
Don’t panic if you see a lien notification.
Use this checklist:
- Check the lien amount.
- Find the reason.
- Contact your bank through an official channel.
- Ask for the reference number.
- Keep copies of your documents and correspondence.
- Resolve the underlying issue.
- Confirm that the lien has actually been removed.
If the bank cannot explain the restriction clearly, ask for the details in writing.
Common Mistakes to Avoid
Assuming the Entire Account Is Frozen
A lien may affect only a particular amount.
Check instead: your available balance and lien amount separately.
Ignoring the Lien
Leaving the issue unresolved can prevent you from using the affected funds.
Check instead: why the lien was placed and what action is required.
Assuming Every Lien Is Related to a Loan
Liens can also arise from disputes or instructions from authorities.
Check instead: ask your bank for the exact reason.
Sharing Banking Credentials
You should never provide your OTP, PIN or password to someone promising to remove a lien.
Check instead: use your bank’s official branch, app, website or customer-care channel.
Key Points to Remember
- A lien is a hold or claim over a specific amount, deposit or asset.
- The lien-marked amount generally cannot be withdrawn.
- You may still have access to money above the lien amount.
- An FD can have a lien when it is used as loan security.
- A transaction dispute or authority instruction can also result in a lien.
- The removal process depends on the reason.
- Always ask your bank for the reason if you don’t recognise the lien.
Conclusion
A lien in banking means that a bank has restricted a particular amount, deposit or asset because of an obligation or specific instruction. It does not necessarily mean that your entire bank account is frozen.
If you see a lien marked on your account, first find out why it was placed and who requested it. Once the underlying issue is resolved, follow the bank’s process to get the lien released.