UPI charges in 2026 do not mean customers must pay extra whenever they transfer more than ₹2,000. The announced rules introduce fees on certain merchant payments from 15 October 2026. Personal transfers remain free. For eligible merchant transactions, the standard fee is 0.4%, capped at ₹300, with exemptions and different rates for specified categories.
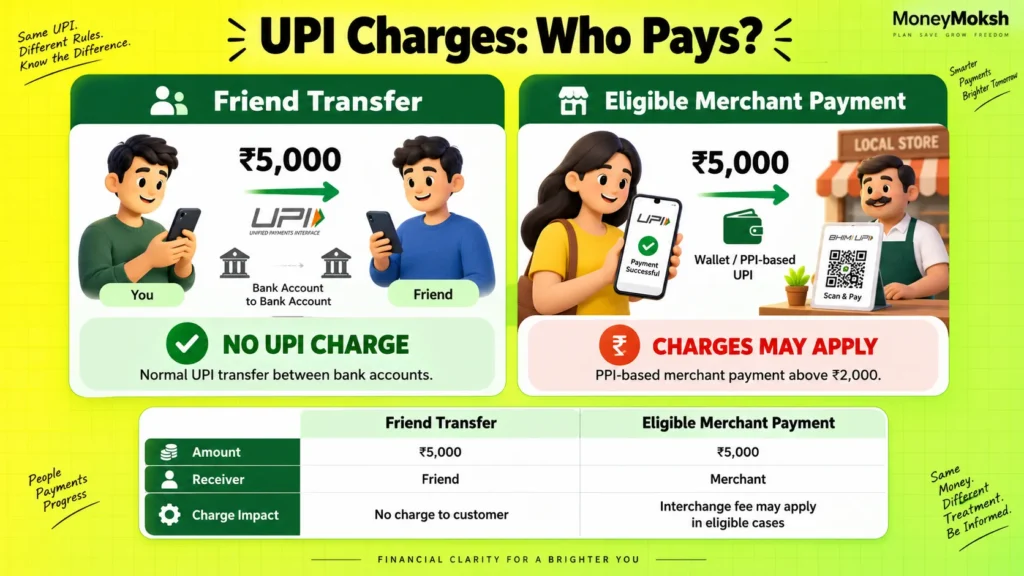
Imagine sending ₹5,000 to your brother and paying ₹5,000 at a clothing shop. Both payments use UPI, but they belong to different categories.
Your brother’s personal transfer remains free. The shop’s payment may attract a merchant fee, depending on its eligibility. That fee is not an extra amount you owe simply for choosing UPI.
Are the New UPI Charges Already Applicable?
The announced merchant-fee framework starts on 15 October 2026. As of 17 September 2026, it has not taken effect.
This distinction matters when reading headlines. An announcement about upcoming charges does not mean the same charges already apply today.
If you run a business, use this time to confirm your merchant category and applicable rate with your payment provider.
Who Pays UPI Charges Above ₹2,000?
For eligible merchant payments, the merchant bears the Merchant Discount Rate, usually called MDR. It is a fee for processing the payment.
The rules do not require customers to add MDR to their bill. Banks have been advised to ensure merchants do not pass this fee to customers.
For example, suppose you buy clothes worth ₹5,000 from a merchant covered by the standard rate:
- Your purchase amount is ₹5,000.
- The calculated merchant MDR is ₹20.
- Your bill should not become ₹5,020 solely because you pay through UPI.
The amount, recipient category and exemption status determine the merchant’s fee.
Which UPI Payments Will Remain Free?
Several categories remain outside the new merchant charges.
| Payment type | Treatment under the announced framework |
|---|---|
| Genuine person-to-person transfer | Free, including transfers above ₹2,000 |
| Merchant payment of ₹2,000 or less | Zero MDR |
| Payment to a qualifying small merchant under the P2PM exemption | Zero MDR |
| Customer making a UPI payment | No customer MDR charge |
Exactly ₹2,000 is included in the zero-MDR threshold. The standard merchant rate concerns eligible transactions above that amount.
Sending Money to Friends or Family
Sending ₹3,000 to a parent or repaying ₹10,000 to a friend does not attract the new merchant fee. These are genuine personal transfers.
A larger transfer may still face your bank’s transaction limit. That is a limit on how much you can send, not a charge for sending it.
Payments to Eligible Small Merchants
The exemption covers qualifying merchants receiving up to ₹1 lakh monthly through UPI QR codes under the Person-to-Person-Merchant, or P2PM, classification.
A shop does not automatically qualify because it looks small. The account classification and eligible receipts matter.
Merchants should confirm their status with their bank or payment provider.
How Much Are the New Merchant Charges?
For standard eligible merchant payments above ₹2,000, the announced MDR is 0.4% of the transaction amount, capped at ₹300 per transaction.
To calculate it, multiply the amount by 0.004 and apply the cap.
Merchant MDR = Transaction amount × 0.004, subject to a maximum of ₹300
| Eligible payment amount | Calculation | Illustrative merchant MDR |
|---|---|---|
| ₹2,500 | ₹2,500 × 0.004 | ₹10 |
| ₹5,000 | ₹5,000 × 0.004 | ₹20 |
| ₹10,000 | ₹10,000 × 0.004 | ₹40 |
| ₹50,000 | ₹50,000 × 0.004 | ₹200 |
| ₹75,000 | ₹75,000 × 0.004 | ₹300 |
| ₹1,00,000 | ₹400 calculated, reduced to the cap | ₹300 |
These examples show MDR only. They do not calculate separate applicable taxes or the complete settlement amount.
Do not use the standard formula for exempt transactions or categories with special rates.
Do All Businesses Pay the Same Rate?
No. Specified sectors have different merchant rates under the announced framework.
For payments above ₹2,000, a flat ₹5 MDR applies to the listed essential sectors:
- Railways
- Telecommunications
- Insurance
- Fuel
- Agricultural inputs
Capital-market payments, including the specified mutual fund, securities and stockbroker categories, have an announced MDR of 0.02%, capped at ₹300.
For illustration, 0.02% of ₹50,000 is ₹10. That differs from the ₹200 calculated at the standard 0.4% rate.
A business should check its assigned category before estimating its payment costs.
Is There a Monthly Limit on Free UPI Payments?
The announced framework does not introduce a monthly quota of free personal UPI transactions.
However, free usage does not mean unlimited transfer amounts. Your bank or payment provider can still apply security and transaction limits.
For example, a message saying “daily limit exceeded” does not mean you must pay to continue. Check the stated limit and when it resets.
Do not confuse the small-merchant receipt threshold with an individual’s monthly allowance. They apply to different situations.
If a payment exceeds your UPI limit, understanding how NEFT transfers work can help you compare another bank-transfer option. Check its applicable charges and processing time first.
What If a Shop Asks You to Pay Extra for UPI?
Ask why the amount has increased before approving the payment.
You can say: “Is this extra amount being charged only because I am paying through UPI?”
Check whether the charge appears on the bill. If it is described as MDR, ask the merchant to explain why it is being passed to you.
If the issue remains unresolved:
- Keep a copy of the itemised bill.
- Save any screen showing the additional charge.
- Record the merchant name, date and disputed amount.
- Raise the issue through your payment app or bank’s official support.
- Keep the complaint reference and response.
For a completed payment, save its UTR or transaction reference number too. Clear records help explain the difference between the original bill and the amount paid.
Checking the final bill and reviewing your payment history are useful ways to manage online spending and spot unnecessary expenses.
What Should Shop Owners Check Before 15 October?
Start by asking your payment provider for written confirmation of your category and fee.
Check these points:
- Merchant classification: Is your account classified under P2PM or another category?
- Exemption eligibility: Do your receipts meet the applicable conditions?
- Rate: Does zero MDR, the standard rate or a special rate apply?
- Threshold treatment: What happens if your monthly receipts cross the exemption threshold?
- Settlement details: Where will MDR and other applicable amounts appear?
- Support process: Ask whom to contact about an incorrect deduction and confirm the expected turnaround time for resolving your request.
After implementation, compare a few settlements with the confirmed terms.
For example, a ₹10,000 transaction produces ₹40 of MDR at the standard rate. If a statement shows another amount, check the classification and itemised calculation before assuming an error.