Table of Contents
Managing your monthly salary can be challenging when essential expenses, lifestyle spending, and savings compete for the same money. Without a clear plan, it is easy to spend most of your income before setting anything aside for future goals.
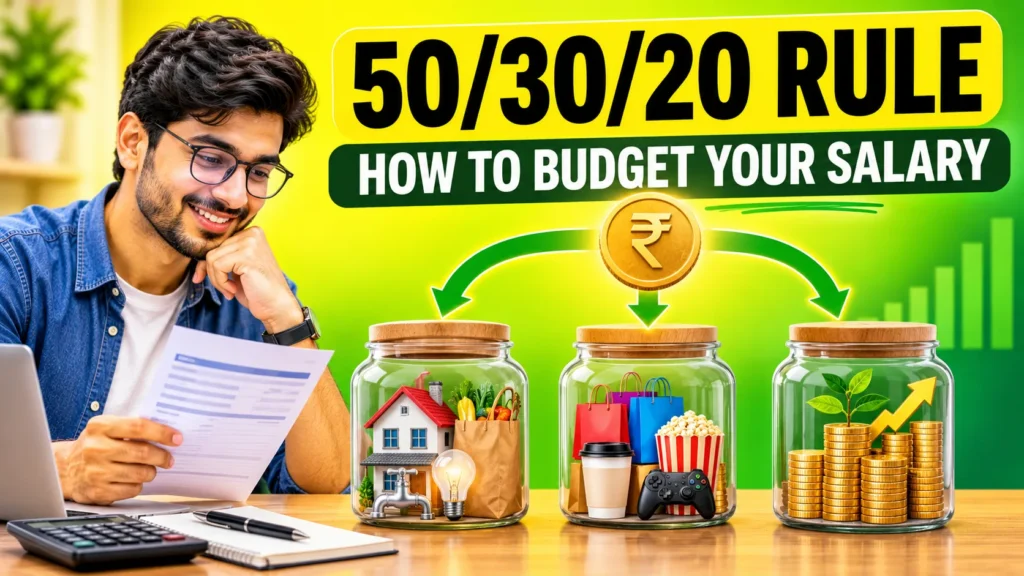
The 50/30/20 rule offers a simple way to approach budgeting salary by dividing your monthly take-home income into three categories: 50% for needs, 30% for wants, and 20% for savings. This method helps you organise your expenses, control unnecessary spending, and build a consistent savings habit without giving up every lifestyle expense.
What Is the 50/30/20 Rule?
The 50/30/20 rule is a budgeting method that divides your monthly take-home income into three portions: needs, wants, and savings. Each category receives a fixed percentage of your income, making it easier to plan expenses and work towards financial goals.
The three categories are:
- 50% for Needs: Essential expenses such as rent, groceries, utility bills, and transportation.
- 30% for Wants: Non-essential spending such as shopping, dining out, entertainment, and holidays.
- 20% for Savings: Money set aside for emergency funds, investments, and future financial goals.
This approach provides a starting point for managing your salary. You can adjust the percentages based on your income, family responsibilities, location, and financial priorities.
How Does the 50/30/20 Budget Rule Work?
The rule works by assigning a purpose to every portion of your monthly income. Instead of spending first and saving whatever remains, you decide in advance how much money should go towards essential expenses, lifestyle choices, and financial goals.
Needs (50%)
Needs are essential expenses that support your everyday living. Ideally, these costs should account for no more than half of your monthly take-home income.
Common examples include:
- House rent or home loan EMI
- Groceries and essential household items
- Electricity, water, and internet bills
- Transportation and fuel
- Essential healthcare expenses
- Insurance premiums and minimum debt repayments
For example, if your monthly take-home salary is ₹50,000, you can allocate ₹25,000 towards these expenses. If your essential costs regularly exceed this limit, review your fixed expenses and adjust the other categories realistically.
Wants (30%)
Wants include expenses that improve your lifestyle but are not essential for daily living. This category allows you to enjoy your income while keeping discretionary spending under control.
Examples include:
- Dining out and ordering food
- Shopping for non-essential items
- Movies and entertainment
- OTT and other subscriptions
- Holidays and leisure activities
- Upgrading gadgets when your existing ones still work
With a monthly take-home salary of ₹50,000, the suggested allocation for wants is ₹15,000. Keeping track of these expenses can help prevent small purchases from affecting your savings goals.
Savings (20%)
The final 20% of your income is allocated towards financial security and future goals. This portion can include emergency savings, long-term investments, retirement planning, and additional debt repayment.
Depending on your financial situation, you can consider:
- Building an emergency fund
- Saving for short-term financial goals
- Investing through suitable mutual funds or other financial products
- Contributing towards retirement goals
- Repaying high-interest debt faster
For someone earning ₹50,000 per month, the suggested savings allocation is ₹10,000. If you are building an emergency fund, consider prioritising that before taking additional investment risks.
50/30/20 Budget Rule: Example
Consider a person earning ₹50,000 as monthly take-home salary. Using the 50/30/20 rule, the income can be divided into three categories as follows:
| Budget Category | Allocation | Monthly Amount |
|---|---|---|
| Needs | 50% | ₹25,000 |
| Wants | 30% | ₹15,000 |
| Savings | 20% | ₹10,000 |
| Total | 100% | ₹50,000 |
This allocation gives the individual a clear spending limit for each category. Essential expenses receive priority, lifestyle spending stays within a planned limit, and a portion of the salary is reserved for future financial needs.
The same calculation can be applied to different salary levels by multiplying take-home income by 0.50, 0.30, and 0.20.
How to Apply the 50/30/20 Rule to Your Monthly Salary
Following the rule becomes easier when you turn it into a monthly routine. These steps can help you organise your salary and understand where your money goes.
1. Calculate Your Monthly Take-Home Salary
Start with the amount credited to your bank account after applicable payroll deductions, rather than your annual CTC or gross salary. This gives you a realistic figure to use for monthly budgeting.
If you also earn money through freelancing, rental income, or other sources, account for that income separately and include it only when it is reasonably predictable.
2. List Your Monthly Expenses
Review your bank statements, UPI transactions, bills, and credit card statements to understand your spending habits. Include both fixed expenses, such as rent and EMIs, and variable expenses, such as groceries, fuel, and dining out.
Tracking your expenses for at least one month can help you identify where your salary is going and which costs can be reduced.
3. Divide Expenses into Three Categories
Classify each expense as a need, want, or savings contribution. Be careful not to treat every regular payment as an essential expense. For example, a basic mobile connection may be a need, while an expensive phone upgrade is generally a want.
This classification helps you compare your actual spending with the suggested 50/30/20 allocation.
4. Set Your Monthly Spending Limits
Calculate the amount available for each category and use it as a spending guideline. You can maintain separate bank accounts, savings goals, or budgeting categories to keep track of your allocations.
Setting aside the savings portion soon after receiving your salary can also make it easier to avoid spending that money unintentionally.
5. Review and Adjust Your Budget
Check your spending at the end of each month. If your needs exceed 50%, look for practical ways to reduce expenses or adjust the other categories without compromising essential requirements.
Your budget should reflect your actual financial circumstances rather than forcing you to follow percentages that may not be realistic.
Benefits of the 50/30/20 Rule
The 50/30/20 rule provides a simple structure for managing income and balancing current expenses with future financial goals.
Encourages Regular Savings
Allocating a specific portion of your salary towards savings helps develop a consistent saving habit. Instead of waiting until the end of the month, you make savings part of your financial plan from the beginning.
Makes Budgeting Simpler
The method uses three broad categories, so you do not need a complicated spreadsheet to get started. It gives you a straightforward way to understand how much you can spend, save, and allocate towards essential expenses.
Helps Control Unnecessary Spending
Setting a limit for wants makes discretionary spending easier to monitor. You can enjoy shopping, entertainment, and other lifestyle activities while keeping them within a planned budget.
Supports Long-Term Financial Goals
Regular savings can help you prepare for emergencies, education expenses, retirement, and other important goals. Over time, a consistent approach can make it easier to plan for these financial commitments.
Is the 50/30/20 Rule Suitable for Everyone?
The 50/30/20 rule is a useful starting point, but it may not suit every income level or household. People living in expensive cities, supporting family members, managing large EMIs, or dealing with irregular income may find it difficult to keep essential expenses within 50%.
For example, someone with high rent and family responsibilities may need to allocate 60% towards needs, 25% towards wants, and 15% towards savings initially. This can be more realistic than following the standard split without considering actual expenses.
The important thing is to maintain control over spending and build savings consistently. You can gradually adjust your allocation as your income increases, debts decrease, or financial responsibilities change.
Tips to Make Salary Budgeting More Effective
A budgeting method works best when you follow it consistently and review it as your financial situation changes.
- Automate savings: Set up a recurring transfer after your salary is credited so that you do not have to rely entirely on monthly discipline.
- Build an emergency fund: Keep money aside for unexpected expenses such as medical bills, job loss, or urgent repairs.
- Review subscriptions: Cancel services and memberships that you rarely use.
- Avoid unnecessary debt: Be careful with credit card spending and high-interest loans that can put pressure on your monthly budget.
- Set specific financial goals: Decide how much you need for short-term and long-term goals, and plan your savings accordingly.
- Review your expenses regularly: Check your spending every month and make adjustments when necessary.
Conclusion
The 50/30/20 rule offers a practical starting point for budgeting salary and managing monthly expenses. By dividing your take-home income into needs, wants, and savings, you can create a clearer spending plan and develop better financial habits. The percentages do not have to be rigid; adjust them to your income and responsibilities while making consistent progress towards your savings goals.
Frequently Asked Questions
1. What is the 50/30/20 rule for budgeting salary?
The 50/30/20 rule is a budgeting method that allocates 50% of take-home income to needs, 30% to wants, and 20% to savings. It helps individuals organise monthly expenses and plan their financial goals.
2. How does the 50/30/20 rule work on a ₹30,000 salary?
For a monthly take-home salary of ₹30,000, the suggested allocation is ₹15,000 for needs, ₹9,000 for wants, and ₹6,000 for savings. You can adjust these amounts based on your essential expenses and financial responsibilities.
3. Should I use gross salary or in-hand salary for the 50/30/20 rule?
It is generally more practical to use your monthly in-hand salary, which is the amount credited to your bank account after payroll deductions. This helps ensure that your budget is based on money actually available for spending and saving.
4. What should be included in the 20% savings category?
The savings category can include emergency funds, investments, retirement savings, and money reserved for future financial goals. You can also use part of this allocation to repay high-interest debt faster.
5. What if I cannot save 20% of my salary?
Start with an amount you can realistically afford, even if it is less than 20%. Review your expenses, reduce non-essential spending where possible, and gradually increase your savings allocation as your financial situation improves.